
A few months ago, a client called me in a bit of a panic. Her parents’ Super Visa had just been approved, flights were booked, and she suddenly realized she hadn’t sorted out the insurance yet — the one thing that could hold everything up. This happens more often than you’d think. Super Visa insurance tends to be an afterthought until it’s not, and by then people are scrambling.
If you’re in Edmonton and going through this right now, here’s the good news: it’s not complicated once someone actually explains it properly. Let’s go through it.
Why You Can’t Skip This Step
Canada’s Super Visa lets parents and grandparents stay for up to five years at a time instead of the usual six months on a regular visit. But the trade-off is that IRCC wants proof you’ve thought about their healthcare. Specifically, they want to see private medical insurance — at least $100,000 worth — from a Canadian insurer, valid for a minimum of one year.
Without that proof, the visa application doesn’t move forward. It’s non-negotiable, which is exactly why it’s worth getting right the first time instead of grabbing whatever pops up first in a Google search.
Edmonton’s Situation Is a Bit Different Than People Assume
A lot of families searching “super visa insurance Edmonton” expect there to be some special Edmonton-only version of this insurance. There isn’t, really — the federal requirements are the same whether your parents are landing in Edmonton, Calgary, or Toronto.
What does matter locally is who you’re buying from. Edmonton has seen a steady increase in Super Visa applications over the past few years, and with that comes a flood of insurance ads promising the “cheapest rate in Alberta.” Some of those are fine. Others quietly exclude pre-existing conditions or make refunds nearly impossible to claim. The insurance itself isn’t Edmonton-specific, but your experience buying it absolutely depends on who’s selling it to you.
The Coverage Details That Actually Matter
Here’s where I’d focus your attention instead of just comparing sticker prices:
Pre-existing conditions. If your mom has managed high blood pressure or your dad has type 2 diabetes, don’t assume that’s automatically covered. Some insurers offer “stable condition” clauses that cover it as long as the condition hasn’t changed recently. Others exclude it entirely unless you pay extra. Ask this question before anything else.
What happens if the visa gets denied. Reputable insurers refund your premium, sometimes in full, sometimes minus a small admin fee, if the Super Visa application doesn’t get approved. If a provider is vague about this, that’s a red flag.
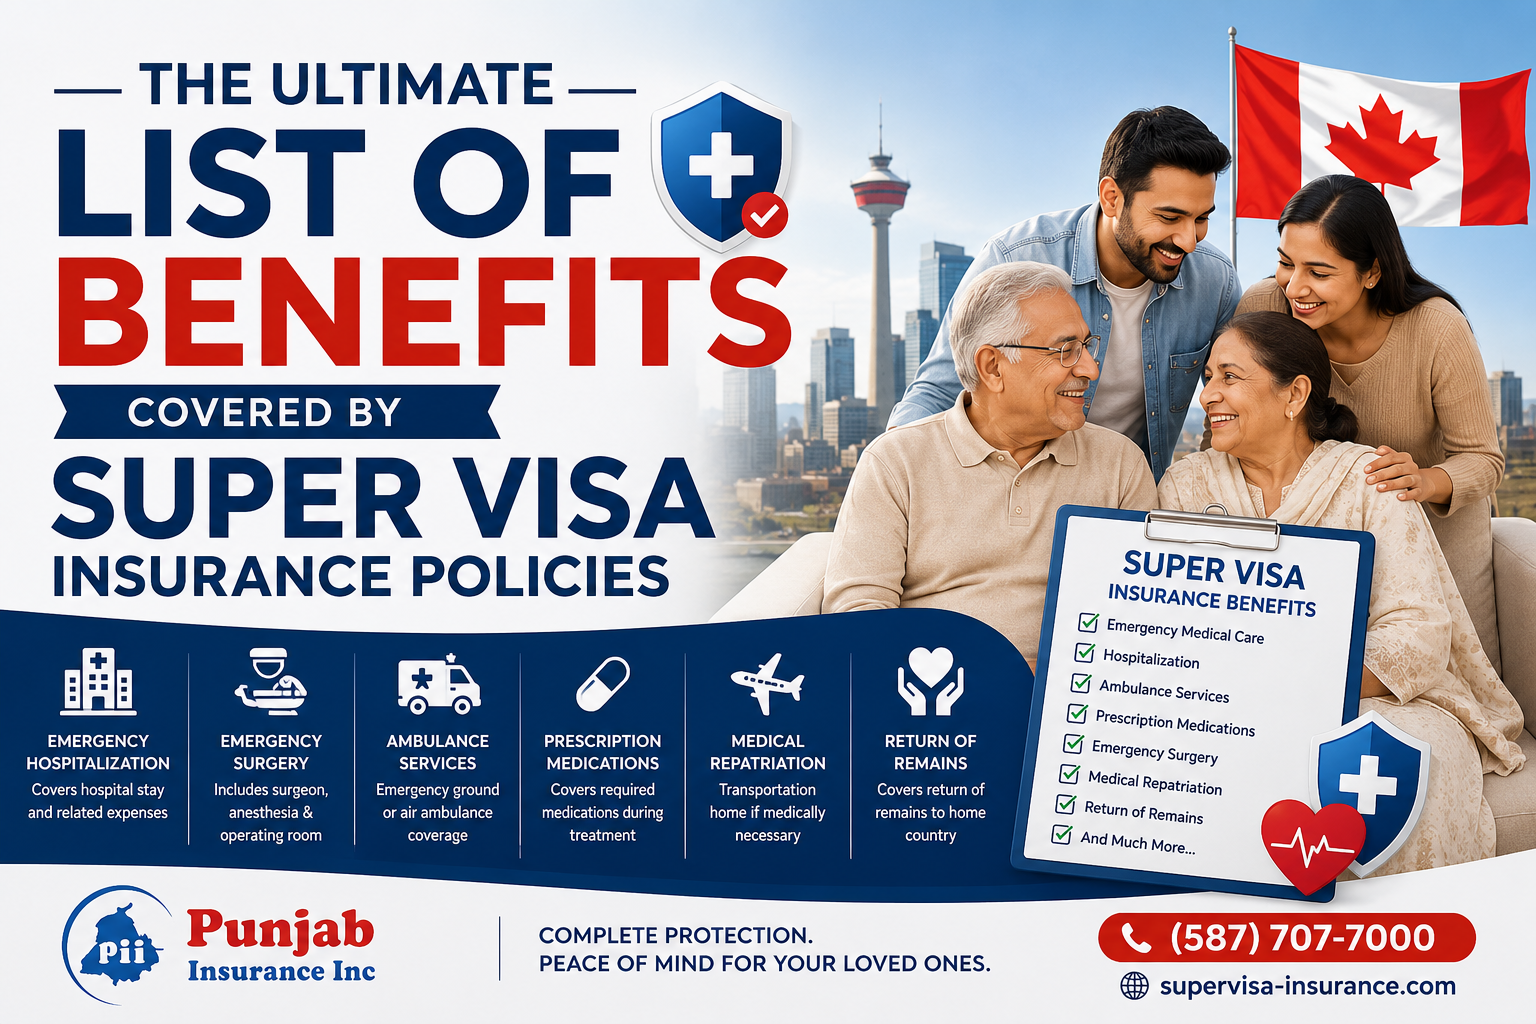
Emergency repatriation. This is the coverage nobody thinks about until they need it — flying someone home for serious medical treatment. It should be included, not an add-on.
How claims actually get processed. This one’s hard to judge from a website. It’s worth asking a broker directly: what happens when my parent actually needs to use this? How fast do claims get paid?
Monthly vs. Annual: An Honest Take
Everyone asks this, so here’s the honest answer: annual plans are usually a bit cheaper in total, but monthly plans exist because most families are already spending a lot getting parents here — flights, gifts, prepping the house. Spreading the insurance cost out isn’t a bad financial decision. It’s just a different one. As long as the monthly plan still meets the $100,000 minimum and one-year validity requirement, either option works for the visa itself.
Why the Broker You Choose Actually Matters
This is where I’ll be direct: you can buy Super Visa insurance from almost anywhere, including websites with zero human contact. But insurance brokers in Edmonton, Alberta — or anywhere in the province, honestly — earn their fee by doing something a website can’t: catching problems before they become expensive.
A decent broker will ask about your parents’ actual health history instead of letting you self-select a plan online. They’ll flag if a “cheap” plan has a deductible that makes it not actually cheap once you do the math. And if a claim ever needs to be filed, you’re calling someone who already knows your file, not starting from zero with a call center.
That’s the entire value proposition, really. Not lower prices — better decisions.
How I Work With Edmonton Families at Punjab Insurance Calgary
Punjab Insurance Calgary doesn’t change anything about how this works for Edmonton clients — most of what I do happens over the phone or by video call anyway. What I focus on:
- Getting you real quotes from multiple providers (GMS, RIMI, 21st Century, Manulife) so you’re not stuck with just one company’s pitch
- Going through pre-existing conditions honestly so there are no surprises later
- Helping you decide between monthly and annual based on your actual budget, not a sales pitch
- Being available if a claim ever needs to be filed — not disappearing after the sale
A Few Mistakes I See Often
- Buying the lowest-priced plan without checking the deductible or pre-existing condition clause.
- Not being upfront about a parent’s health history, which can cause a claim to get denied later.
- Forgetting to double-check the refund terms before purchasing.
- Leaving it until the last week before the visa is meant to start — give yourself breathing room.
Frequently Asked Questions
Do I need Edmonton-based insurance if my parents are landing there? No. Super Visa insurance requirements are federal, not city-specific. What matters is that the policy meets IRCC’s minimum coverage and validity rules — where your broker is physically located doesn’t affect that.
What if my parents already have a health condition?
Most insurers will still cover them, but the terms depend on the condition. Being transparent about it upfront is the only way to avoid a denied claim later.
Can I get a refund if the visa is refused?
In most cases, yes — typically a full or near-full refund, as long as coverage hadn’t already started. Always confirm this specific policy’s terms before buying.
How much should I actually expect to pay?
It varies a lot based on age and health, but most families budget anywhere from a few hundred to a couple thousand dollars a year. A personalized quote is really the only way to know for sure.
Is it better to work with a local broker instead of buying online directly?
It depends on your comfort level, but a broker can catch issues in the fine print that are easy to miss on your own — especially around pre-existing conditions and claims processes.
If you’re working through this for your own family, I’m happy to walk you through the options and get you a real quote instead of a generic one.